


Roof damage and insurance: when it covers, when you get reduced payout
The short answer
Home insurance covers sudden and unforeseen roof damage — storm, lightning, a tree falling on the roof. It does not cover damage that has built up over time due to wear or lack of maintenance. The roof itself is your responsibility to maintain and repair — insurance only covers interior follow-on damage, and only if the cause was sudden. Without documented maintenance, you risk reduced payout or full rejection. This applies across all major insurers: If, Gjensidige, Fremtind, Storebrand, SpareBank 1 and DNB.
Does home insurance cover roof damage?
Yes — but only if the damage is sudden and unforeseen. That's the single rule that drives almost every claim at Norwegian insurers.
Roof damage that is covered:
- A tree blown onto the roof in a storm
- Lightning strike on chimney or roof
- Tiles torn off by hurricane-strength wind
- Hail breaking roof windows
- Fire damage
Roof damage that is NOT covered:
- A roof leaking because the felt is 30 years old
- Moss holding moisture against tiles for years → cracks → leak
- Rot in the underlayment that has developed gradually
- Condensation damage from poorly ventilated attic
- Leaks around chimney or flashings that got worse over time
Terms are broadly similar at If, Gjensidige, Fremtind, Storebrand, SpareBank 1 and DNB. The difference is in extended coverage such as Storebrand Super or Gjensidige Topp — these cover follow-on damage from leaky roofs on buildings up to around 50 years old, but never the roof itself.
What does "reduced payout" (avkortning) mean?
Reduced payout means the insurer reduces your payout because you haven't met your obligations as policy holder. It's not all-or-nothing — the company can cut the payout partially (typically 20–50 %) or reject the claim entirely.
The three most common reasons for reduction on a roof claim:
- Lack of maintenance that led to or worsened the damage
- Known damage you didn't address (e.g. "it's been dripping a little for two years")
- Gross negligence in handling once the damage occurred
A classic: a roof that has leaked gradually for several years. When the damage is finally discovered, the insurer may cover the interior follow-on damage (contents, floor) but reduce or reject the building portion because the roof has clearly been in bad shape for a long time. Finansklagenemnda (the Financial Complaints Board) has a long list of cases on exactly this.
Why the roof is a special case
The roof itself is never covered by insurance — regardless of company, regardless of coverage level. It's your responsibility to maintain.
What insurance can cover is interior follow-on damage if the cause of the leak was a sudden event. If the cause is gradual wear, coverage on the follow-on damage normally also lapses.
| What | Covered by standard home insurance? |
|---|---|
| The roof itself (tiles, felt, flashings) | No — never |
| Interior follow-on damage from storm / lightning | Yes |
| Interior follow-on damage from gradual leak | Usually no |
| Follow-on damage from leaky roof ≤50 years old | Yes, with extended coverage (Super/Topp) |
| Gutters torn down by snow | Yes (sudden) |
| Underlayment rot from poor maintenance | No |
| Mold and fungus from leak over time | Usually no |
| Damage to contents (furniture, TV, clothes) | Yes, via contents insurance |
What does the insurer expect from you?
To avoid reduced payout, you need to be able to document that you've fulfilled the maintenance duty written into your policy. Specifically:
- Regular roof inspection — at least every other year, ideally annually in Bergen climate
- Timely gutter cleaning — clogged gutters are one of the most common triggers of claims that end in reduced payout
- Fixing small damage before it grows
- Documentation of maintenance and repairs — receipts, reports, photos
- Authorized tradesmen on plumbing and membrane work
- FG-approved safety equipment where required (e.g. water stops)
Insurance is a contract: the company pays for sudden accidents, you take care of the building. Break your side, and they reduce or deny theirs.
Two typical scenarios
Scenario 1 — Full claim rejection:
Owner discovers moisture damage in the attic. It turns out the roof has had a small leak for 3–4 years, and moss has built up on the tiles over a long period. The insurer rejects the entire claim because the damage is gradual and due to lack of maintenance.
Scenario 2 — 30 % reduced payout:
A tree falls on the roof in a storm. Insurance covers the immediate damage and interior follow-on damage, but reduces the payout by 30 % because the roof's general condition was poor and worsened the extent.
In both cases, documented regular inspection would have changed the outcome.
Book free roof inspection and get documentation →
Practical checklist to keep your insurance coverage
- Carry out a thorough roof inspection at least every other year
- Save documentation: a short report with photos after each inspection can be decisive later
- Read your policy terms — especially safety requirements and maintenance duty
- Report damage quickly — delay increases both reduction risk and damage extent
- Use authorized tradesmen and keep the receipts
Also read 7 signs your roof needs a look for concrete signals you can spot yourself.
Free documented roof inspection in Bergen
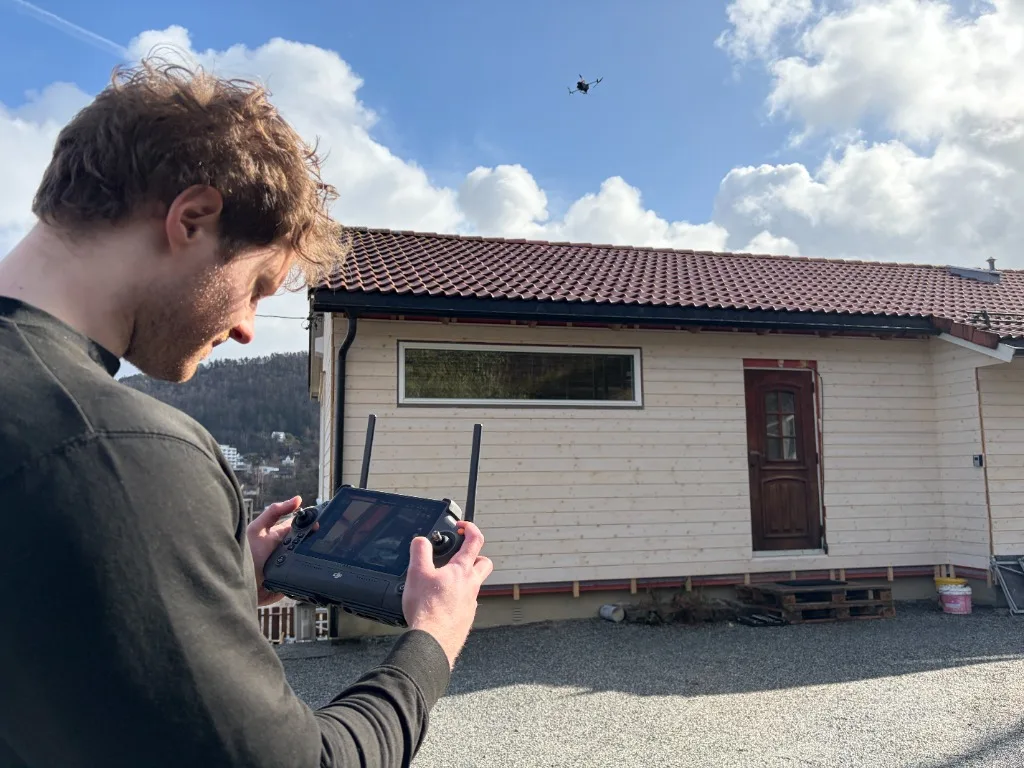
We perform free drone inspection with 3D model and condition report in Bergen, Askøy, Øygarden, Bjørnafjorden, Alver and Osterøy. The report is documentation you can file away — for insurance claims, a future sale, or your own peace of mind.
Or call Henrik directly on +47 903 62 498.
Sources
- DNB — Home maintenance and damage prevention
- Storebrand — Most common home insurance claims
- SpareBank 1 — What home insurance covers
- Gjensidige — Home insurance
- Huseierne — Insurance does not cover roof leaks
- Finansklagenemnda — Practice on reduced payout for lack of maintenance
Important disclaimer: This is general information based on the terms of the largest Norwegian insurers in 2026. For your specific situation, always read your own policy terms or contact your insurer directly. We are not insurance advisers.
Frequently asked questions
Does home insurance cover roof leaks?
How old can the roof be before insurance stops covering?
What's the difference between home and contents insurance for roof damage?
Can the payout be reduced even if the damage was sudden?
What do I do if insurance reduces the payout unreasonably?
Do I have to document roof maintenance?
Does insurance cover damage from ice dams or icicles?
What's the deductible on a roof claim?
Need help with your roof?
We offer a free roof inspection with drone, 3D model and detailed report. No commitment.